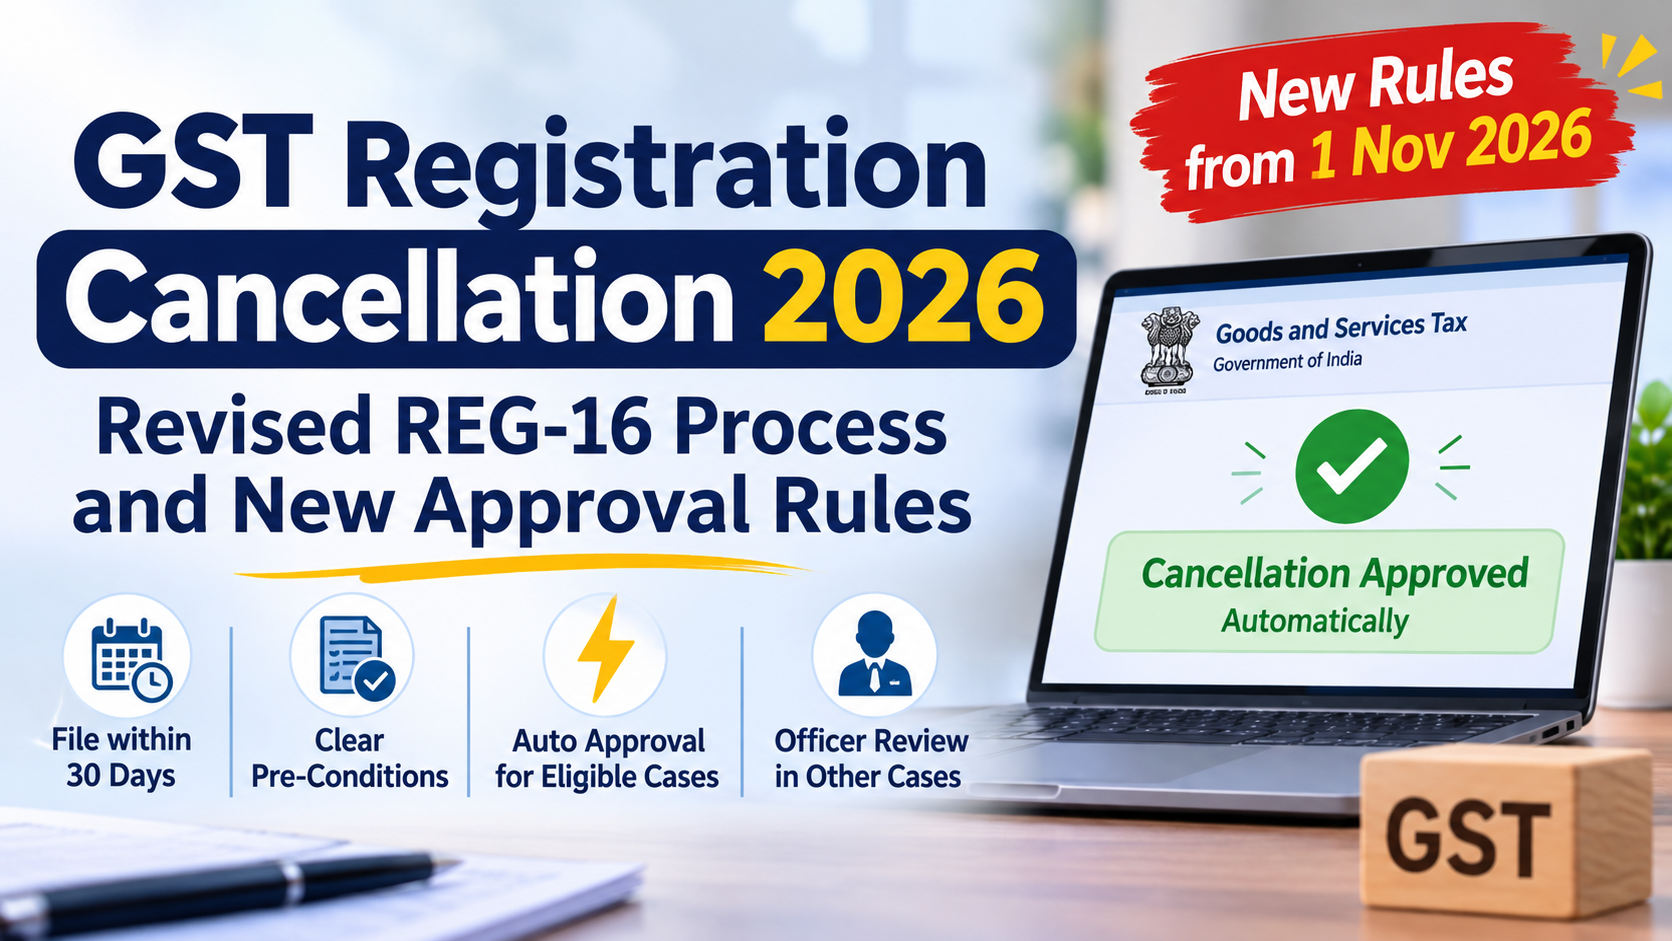
From 1 November 2026, the GST portal approves most cancellation requests on its own. No officer. No 30-day wait. No random query on your PPOB.
The catch is simple. The system checks your returns and your tax numbers first. Miss one return and your file goes back to the officer.
The change comes from Notification No. 05/2026-Central Tax dated 26 October 2026, which substitutes Rule 20 of the CGST Rules. The 57th GST Council recommended it on 8 October 2026. GSTN followed with Advisory No. 683 dated 1 November 2026 on how the portal will process REG-16.
Quick answer for busy owners:
Need help cancelling your GST registration? Chhota CFO can help you complete the cancellation process, clear pending returns and avoid filing mistakes.
Get GST Cancellation Support | +91 97397 36999
The biggest shift: approval moves from the officer’s desk to the portal for compliant taxpayers.
Point | Before 1 Nov 2026 | From 1 Nov 2026 |
Governing rule | Rule 20 read with Rule 22(3) | Substituted Rule 20 |
Who approves | Officer, by order in REG-19 | Portal, for eligible cases. Officer for the rest |
Officer time limit | 30 days from application | 15 days from application or reply |
Officer delay | No relief | Deemed approved |
Pending returns | Filed during or after the process | Must be filed before you submit REG-16 |
Status while pending | Active | Suspended from the application date |
Cancellation order | REG-19 | REG-38 (system) or REG-19 (officer) |
Effective date change by officer | No set procedure | Notice in REG-34, once only, with a 60-day limit |
ITC reversal reporting | ITC-03 | Inside REG-16 itself (from 1 Dec 2026) |
Key dates to note:
Date | What takes effect |
1 Nov 2026 | New Rule 20, system approval, new forms REG-34 to REG-38 |
1 Dec 2026 | Revised REG-16 form and amended Rule 44 (ITC reversal) |
1 Apr 2027 | System-led suspension, cancellation and revocation for non-filers under new Rules 21A, 22 and 23A |
Source: TaxGuru analysis of CGST Amendment Rules 2026 and SAG Infotech summary.
You file REG-16 under Section 29(1) of the CGST Act when one of these events happens:
The 30-day rule: file within 30 days of the event. A business closed on 10 November 2026 must file by 10 December 2026.
One exception: on the death of a sole proprietor, the 30-day limit does not apply. The legal heir files on behalf of the deceased.
Pre-conditions before you click submit:
What happens once you submit: your registration is suspended from the application date. You stop issuing tax invoices. You still file returns for the period up to the cancellation date, by their normal due dates.
The portal runs five checks in order. Pass all of them and you never meet an officer.
REG-16 approval flow · 5 checks, 2 outcomes
Fail any check and the file moves to the officer, who still has only 15 days.
How to file on the portal:
Your category decides the route. Returns filed on time is the gate for every category.
Taxpayer category | Test after returns are filed | Result |
Composition taxpayer | None | Automatic approval |
Input Service Distributor (ISD) | None | Automatic approval |
Non-Resident Taxable Person (NRTP) | None | Automatic approval |
OIDAR supplier | None | Automatic approval |
Regular, casual or SEZ, output tax up to ₹2.5 lakh in every month | ₹2.5 lakh test passed | Automatic approval |
Regular, casual or SEZ, output tax above ₹2.5 lakh in any month | GSTR-10 filed within 3 days | Automatic approval |
Regular, casual or SEZ, GSTR-10 not filed in 3 days | Failed | Sent to officer |
Any category, returns not filed on time | Failed | Sent to officer |
How the ₹2.5 lakh test works:
What ₹2.5 lakh output tax means in sales terms: at 18% GST, it equals taxable sales of about ₹13.9 lakh in a month. At 5%, it equals ₹50 lakh.
The 3-day GSTR-10 window: if your application sits in the Pending for Returns Filing stage, the 3 days run from the due date of those pending returns. If no returns are pending, the 3 days run from the date you submit REG-16. File on time and the portal approves. Miss it and the officer takes over, with the normal 90-day GSTR-10 deadline from the cancellation date.
Once approved, the portal issues REG-38. The cancellation takes effect from the date you asked for in REG-16.
Not sure whether your business qualifies for automatic GST cancellation? Get expert assistance with eligibility checks, pending returns and GSTR-10 filing.
The officer route now runs on fixed clocks. Delay by the department works in your favour.
Step | Who acts | Form | Time limit |
Officer cancels or raises a query | Officer | REG-19 or REG-03 | 15 days from application |
You reply to the query | You | REG-04 | 15 days from the query |
Officer decides on your reply | Officer | REG-19 | 15 days from your reply |
Officer misses a deadline | Portal | REG-19 (deemed) | Deemed approved |
You ignore the query | Portal | REG-05A | Deemed rejected |
Officer changes your cancellation date:
Why the date matters: an earlier date pulls back your return obligations and your ITC reversal. Example: you asked for 30 November 2026, the officer proposes 30 June 2026. Five months of invoices then fall after cancellation. Reply to REG-34 with your sales and purchase records.
As per TaxGuru’s registration overhaul analysis.
The new form does three things:
Worked example 1: automatic approval
Sharma Traders, Jayanagar, Bengaluru. Monthly filer. Closes shop on 15 November 2026. Highest monthly output tax since registration: ₹1.8 lakh.
If one month had shown ₹4.2 lakh output tax, Sharma Traders files GSTR-10 within 3 days of 20 December, by 23 December 2026, and still gets automatic approval.
Worked example 2: ITC reversal in REG-16
Section 29(5) requires you to pay back ITC on stock held on the cancellation date. For capital goods, Rule 44 reduces ITC by 5 percentage points for every quarter of use, and you pay the higher of this amount or tax on the sale value.
Item | Value (₹) | ITC taken (₹) | Reversal (₹) | Working |
Raw material in stock | 4,00,000 | 72,000 | 72,000 | Full ITC on inputs held |
Finished goods in stock | 6,00,000 | 60,000 | 60,000 | ITC on inputs inside the goods |
Machine bought 1 Dec 2024 | 10,00,000 | 1,80,000 | 1,08,000 | 8 quarters used, 40% cut, 60% reversed. Higher than ₹90,000 tax on ₹5 lakh market value |
Total |
|
| 2,40,000 | Paid through cash or credit ledger |
Report these figures in the revised REG-16 table. Mismatch with your books invites a REG-03 query and pushes the file to the officer.
Run this checklist before you open REG-16:
Mistakes we see often:
Cancelling your GST registration involves more than submitting Form REG-16. Pending returns, outstanding tax liabilities, ITC reversal and final return filing must also be handled correctly.
Chhota CFO helps businesses manage the complete GST cancellation process with:
The new rules reward clean records. One missed GSTR-3B or a wrong ITC reversal sends your file to the officer and adds weeks.
Chhota CFO handles the full cancellation for you: return clean-up, ₹2.5 lakh test, ITC reversal working, revised REG-16, GSTR-10 and replies to REG-03 or REG-34.